


High-value cargo
Up to $15M
Limits for high-value and theft-prone loads.
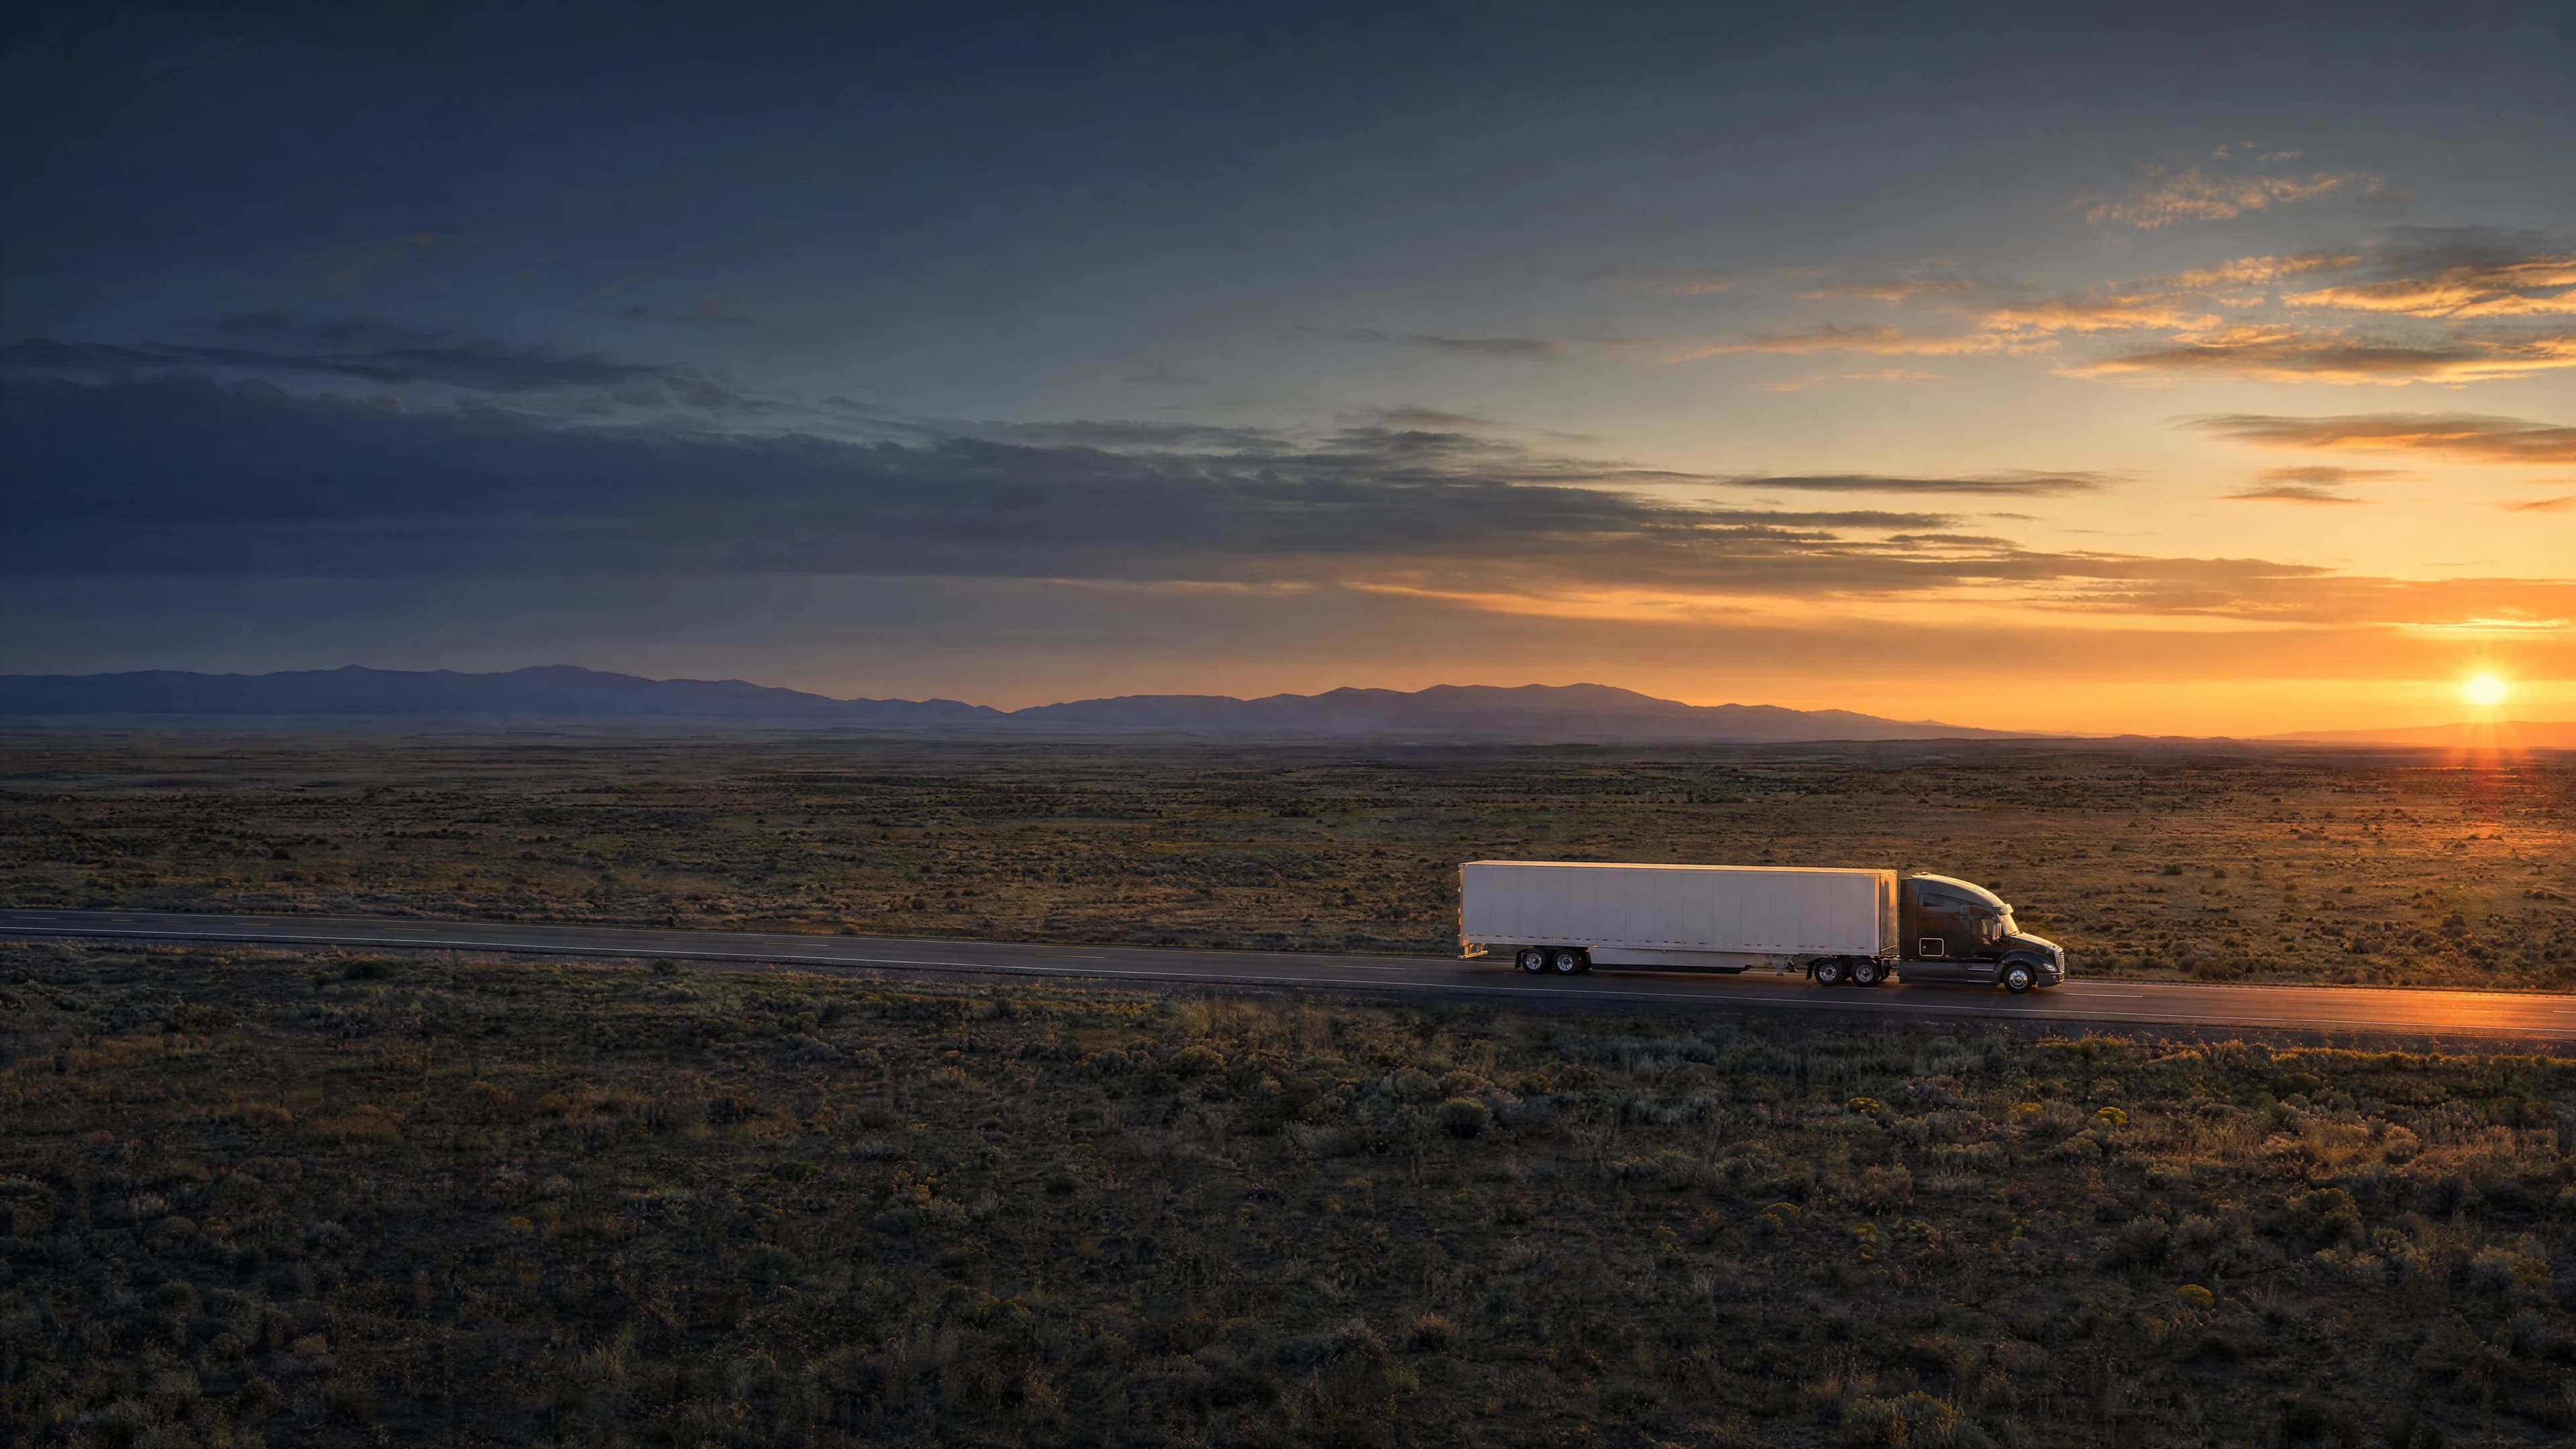
Cargo insurance
Cargo coverage for freight brokers, shippers, and 3PLs, paired with shipment intelligence and an operations team to help prevent losses.
High-value cargo
Limits for high-value and theft-prone loads.
Optional protection
Available with All-Risk or as standalone coverage.
Proactive risk support
Shipment risk platform with 24/7 operator support.
Traditional insurance programs are largely reactive to cargo losses. They address what could or should have been done to prevent or reduce a loss after cargo has been damaged or stolen. Indemni pairs insurance with risk mitigation tools to help customers reduce losses, claims, and disruptions.
In working with our partners, we have a program where the technology was in place before the insurance program. We recognize the need for useful risk mitigation tools that partner with an insurance policy, thereby providing a higher level of security and an improved insurance experience.
High-value freight means freight valued at $250,000 or more per shipment. Most standard carriers won’t insure high-value and theft-prone loads, or if they do, they are only willing to provide limits that are well below the full value. We specialize in protecting those risks when it matters most for our customers.
| Market | Standard carriers | |
|---|---|---|
| Availability | Often declined | Specialist placement |
| Limits | May fall below the full load value | Up to$15M |
Choose whether to include Strategic Theft with All-Risk coverage or cover Strategic Theft alone. Strategic Theft Only excludes all other perils.
Refrigeration Breakdown is available by endorsement.
Commodities we consider, subject to underwriting and policy terms. Household Goods, including furniture and household effects, are not insured.
Processing units, rack servers, storage systems, semiconductor equipment, networking equipment, personal computers, mobile devices, audio & visual gear, robotics, telecom infrastructure.
Fiber optics, copper, steel coil.
OTC drugs, vitamins & supplements.
Beer & wine, frozen foods, food products.
Equipment & machinery.
Loss or damage
All-Risk coverage means just that. Coverage for any cause of loss unless specifically listed as an exclusion in the policy.
Protects a business shipping its own inventory.
Protects the freight broker when the motor truck carrier’s insurance is inadequate or does not respond.
People and policy
We provide Contingent Cargo and Trip Transit insurance built to fit the business needs of freight brokers, 3PLs, and shippers.
Your Indemni team
Partner with our platform and team of operators who specialize in ground-level shipment intelligence.
Cargo insurance covers freight that is damaged, lost, or stolen while in transit or temporary storage. Coverage depends on the selected form.
Freight in transit and temporary storage
Coverage below depends on the selected form. All-Risk is available with or without Strategic Theft. Strategic Theft Only excludes all other perils.
Protects a business shipping its own inventory, by truck, rail, or parcel, when it does not control the motor truck carrier.
A full trailer stolen from a yard, a load taken in a fictitious or double-broker pickup, or freight pilfered in transit.
Freight crushed, scattered, or written off when the truck collides, jackknifes, or overturns.
Freight dropped, crushed, or water-damaged during loading, unloading, or transfer between conveyances.
After a covered loss, the cost to clean up and dispose of damaged cargo, plus the freight charges you had already earned on the load.
To prevent a potential covered loss, freight is covered while it is being moved or being stored for up to 90 days or coverage expiration, whichever comes first.
After a covered loss, the expense to extract pollutants from land or water, if reported within 180 days of the loss.
Covered by commercial auto
Physical damage to the tractor, trailer, or reefer unit is not cargo.
Covered by commercial property
Inventory at rest in a fixed warehouse is not in transit.
Covered by general liability
If the wreck that destroys the freight also injures another driver or damages property other than the covered freight, that injury or property damage claim is liability, not cargo.
Covered by a refrigeration breakdown endorsement
Reefer unit failing and spoiling a perishable load is excluded on most base forms.
See optional coverageNot insured
Furniture and household effects are outside our appetite.
Insurance coverage is subject to eligibility, underwriting, terms, conditions, limitations, and exclusions.
| Scenario | How the claim happens |
|---|---|
| Full-trailer cargo theft | Loaded trailer is stolen from a yard or taken in a fictitious pickup. |
| Reefer breakdown spoils a load | A refrigeration unit fails on a perishable shipment and the entire load is condemned. |
| Collision destroys the freight | A jackknife or overturn crushes or scatters the load. |
| Water and handling damage in transit | Freight is soaked by a roof leak or crushed during a forklift transfer. |
These examples describe cargo losses. Coverage depends on the selected form, endorsements, terms, and limits.
There is no standard limit or coverage. The coverage and limit that best protect you depend on several factors.
Motor Truck Carriers
A motor carrier hauling electronics or pharmaceuticals needs far more on a single trailer than one moving building materials at the same revenue.
Freight Brokers and Shippers
Freight brokers, shippers, and 3PLs will not tender a load until the motor truck carrier submits a certificate of insurance detailing their insurance coverage including limits of insurance.
For contingent cargo coverage, freight brokers are required to obtain proof of the carrier’s insurance limit that is equal to the cargo value.
Annual policy
Cargo value exceeds the annual policy limit
Request an increase for that shipment only
Contingent Cargo policies require the freight broker to obtain proof of the carrier’s insurance before it will tender the load. The carrier’s insurance must be current and with limits that equal or exceed the value of the cargo assigned to them.
The insurance limit for a contingent cargo liability policy should equal their highest shipment value. Indemni offers Contingent Cargo Liability coverage on an annual policy with limits up to $1M. For individual shipments where the cargo value exceeds the annual policy limit, a request can be submitted to Indemni to increase the contingent cargo liability limit to meet the cargo value for that shipment only.
Per shipment · All-Risk coverage
Direct shippers of higher-value freight have two options for insurance coverage. They can require the carrier to provide proof of insurance for cargo, which at most will be $250,000 per load on an All-Risk form, and name the shipper on the certificate before the first pickup.
On a high-value freight shipment, this limit is most likely inadequate. Indemni offers Trip Transit (Single Trip) coverage where we provide All-Risk coverage for the cargo up to $15M per shipment.

Any single loss

One truck or trailer

Same as per-occurrence limit

Endorsement required

of the Limit of Insurance
The most the policy pays for any single loss, which in practice is your worst single load. This is the figure most freight brokers and shippers set as their minimum before they tender freight.
A cap on what is paid for the freight on any one truck or trailer at one time. Carry enough to cover your most valuable load on a single vehicle, not your average.
The most the policy pays for any single loss regardless of the number of modes of transportation involved, or any combination of modes of transportation involved.
The most the policy pays for refrigeration-breakdown spoilage, and only when the endorsement is on the form. High-risk commodities are often sublimited or excluded inside it.
What you pay on each covered claim - deducted from the available amount paid by insurance.
Any freight broker, 3PL, shipper or motor carrier that hauls high-value freight for others. The type of coverage you need depends on your role. Review whether you need contingent cargo liability or shippers-interest coverage, along with the Strategic Theft terms that apply to your freight.
Insurance is recommended, offered and sold by Indemni Insurance Agency, LLC (CA License #6019669). Insurance coverage is available in the states of AZ, CA, FL, GA, IL, IN, KY, MI, MN, NC, NJ, NY, OH, OR, PA, SC, SD, TN, TX, WA, WI, and WV only (09/2026)
Insurance coverage is subject to eligibility, underwriting, terms, conditions, limitations, and exclusions. Please refer to the applicable policy documents for complete coverage details. Program details are subject to change without notice. Underwritten and provided on a surplus lines basis by Chaucer Syndicate 1084 at Lloyds. Surplus lines insurers do not generally participate in state guaranty funds and insureds are therefore not protected by such funds.